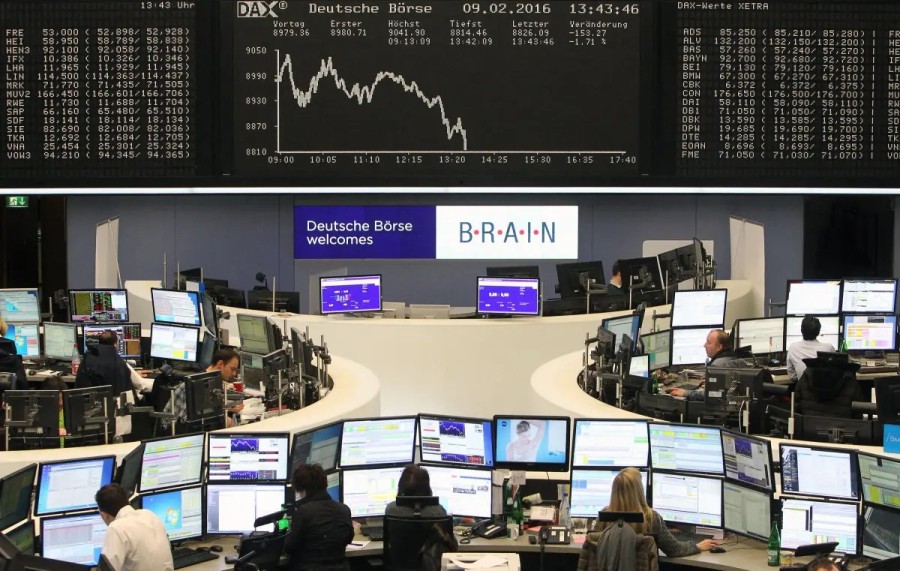
European shares rose slightly on Monday, recovering some of last week's losses, as crude oil prices fell following diplomatic efforts to ease tensions in the Middle East, although caution remained the order of the day ahead of a wave of results from tech giants and key central bank meetings.
The pan-European STOXX 600 index remained largely stable, attempting to hold its ground after falling more than 1% last week under the weight of a sell-off in the technology sector and safe-haven flows fueled by domestic turmoil in France.
Oil prices provided some relief to European energy-importing stock exchanges on Monday, as crude futures fell 1% following reports that Qatari intermediaries had traveled to Tehran on Sunday in coordination with Washington to defuse regional tensions.
This decline came as a welcome relief after Brent crude futures, the international benchmark, jumped 6.2% last week, marking their highest weekly settlement since mid-2022, driven by coordinated drone and missile attacks by the Houthis targeting vital energy and transport infrastructure in Saudi Arabia.
Inflationary pressures threaten an imminent interest rate hike
Despite a slight pullback in oil on Monday, the broader inflationary momentum driven by record high energy levels created a tense atmosphere at institutional trading tables, amid an intense monetary policy agenda this week.
Financial circles agree that global central banks are walking a tightrope, as interest rate hikes are almost certain even if policymakers maintain a wait-and-see approach in the foreseeable future.
Financial markets are predicting that the Federal Reserve will keep its benchmark interest rate unchanged at 3.75%–4.00% this week, but interest rate swaps now indicate an 80% probability of a 25-basis-point rate hike in December.
Similar hawkish paths are being priced in for both Frankfurt and Tokyo. The European Central Bank and the Bank of Japan are both expected to keep interest rates unchanged this week before raising them later in the year or early next quarter to curb persistent energy-related inflationary pressures.
Capital spending on artificial intelligence under scrutiny ahead of cloud service giants' earnings reports
European technology stock exchanges have recovered from their positions following last week's sharp decline, with investors focusing their attention on the US financial disclosure schedule.
Around a third of the companies in the Standard & Poor's 500 index are scheduled to release their quarterly results this week, led by cloud computing and artificial intelligence giants Alphabet, Microsoft Group and Amazon:
Trading tables are intensely focused on management's comments regarding capital expenditure frameworks. Investors' ongoing concerns about excessive debt financing and the long-term prospects for returns on AI investments—which triggered last week's global tech sell-off—will make the capital expenditure guidance of these giants a crucial indicator for European chip equipment suppliers such as ASML and ASM International.
France avoids downgrade from Moody's
While ongoing civil unrest and political gridlock surrounding President Emmanuel Macron’s budget proposals continue to keep institutional investors on edge, Parisian assets drew some relief after credit rating agency Moody’s refrained from downgrading France’s sovereign debt rating late on Friday.
This decision provided much-needed margin for the yields on 10-year US-French Treasury bonds, which had exceeded the psychological level of 5.00% last week to reach their highest levels since 2002.